



版权说明:本文档由用户提供并上传,收益归属内容提供方,若内容存在侵权,请进行举报或认领
文档简介
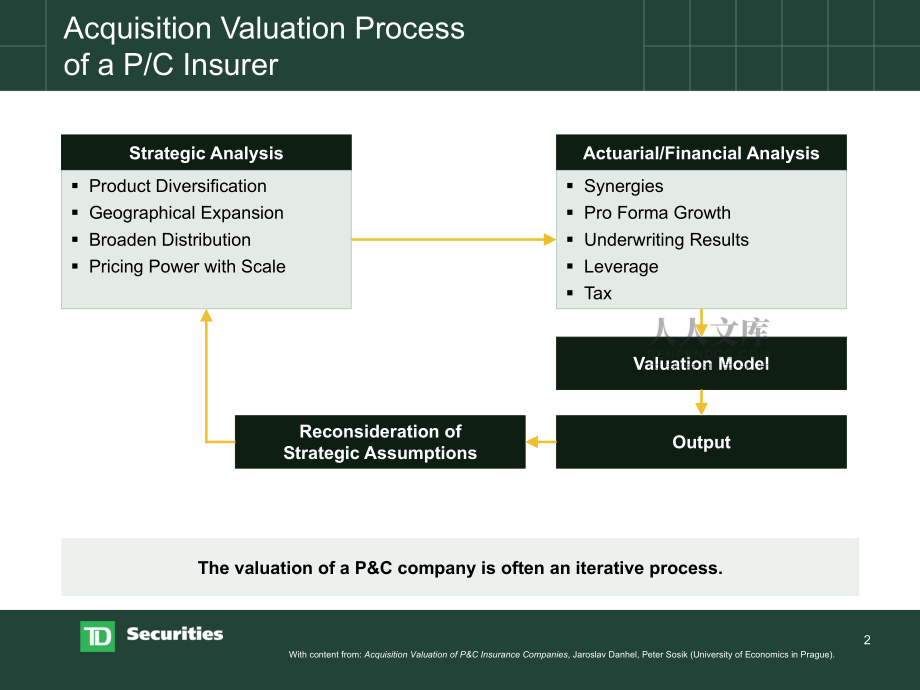
1、Valuation of a P&C CompanyPresented at CAS Spring MeetingJune 16, 2008 Quebec CitySean C. Martin, CFAVice PresidentFinancial Institutions GroupInvestment BankingTD Securities, Inc.2Acquisition Valuation Process of a P/C Insurer With content from: Acquisition Valuation of P&C Insurance Compan
2、ies, Jaroslav Danhel, Peter Sosik (University of Economics in Prague).Strategic AnalysisActuarial/Financial Analysis Product Diversification Geographical Expansion Broaden Distribution Pricing Power with Scale Synergies Pro Forma Growth Underwriting Results Leverage TaxValuation ModelOutputReconside
3、ration of Strategic AssumptionsThe valuation of a P&C company is often an iterative process.3Inputs to Valuation Process ActuarialCompany/Bankers/AccountantsPremium Growth by Business LineLoss & ALAE Ratios by Business LineULAEPayout PatternsExpensesReserve AdjustmentsInvestment YieldTaxCapi
4、tal Structure/Requirements4Valuation MethodsBook Value ApproachValue = value of assets value of liabilitiesAccounting focusedRetrospectiveFuture value of business not considered Stock Market ApproachValue = # of shares X share priceEfficient market hypothesisNo control premiumFuture value of busines
5、s may not be consideredDiscounted Cash Flow Approach (DCF)Value = Valuation of future profitSensitive to assumptionsValidate other methodsTt=1CFt(1-r)tWith content from: Acquisition Valuation of P&C Insurance Companies, Jaroslav Danhel, Peter Sosik (University of Economics in Prague).5Valuation
6、Methods (contd)Relative ValuationComparison to prices of:Precedent TransactionsPublic CompaniesPrice to Earnings (P/E) MultipleP/E = Price per ShareEarnings per ShareEarnings of Target Last-Twelve-Months (LTM) Forward (2008E) Normalized Post-SynergiesPrice-to-Book MultipleP/BV = Price per ShareBook
7、Value per ShareBook Value of Target Current Tangible (excludes Goodwill) Adjusted (reserve adjustments) 1.0 x value to excess capital6 Valuation “Football Field” - ExamplePreliminary Value Range (C$ per share)Comparable Companies plus Control Premium Precedent TransactionsComparable Companies Analys
8、t Target Prices (1)52 Week High - LowHistorical Average Trading Multiples (2)CanadaU.S. Implied Price / Book Value $221.5x$261.7x$302.0 x$181.2x$27.50$20.00$25.00$28.50$27.00$28.00$27.00Source: Bloomberg and Thomson.(1) Based on target prices from four of the seven companies covering XYZ.(2) Range i
9、s from average P/E to average P/BV from January 1, 2005 to January 1, 2007.$28.00$20.00Current Price: $20.00$24.00$23.00$23.00$24.00$25.007Comparable Companies - ExampleMarket Capitalization is on a diluted basis and includes in-the-money exercisable options outstanding.GAAP EPS is used for Canadian
10、 companies. Operating EPS is used for U.S companies and excludes tax realized gains and losses.Based on Bloomberg estimates.Multiples are calculated based on the closing price a day prior to the acquisition announcement by Liberty Mutual.8Precedent Transactions - ExampleSource: Bloomberg, SDC, MSA R
11、esearcher and various news servicesPrice/Earnings value calculated using 1H 2007 annualized net income.Price/Book value based on TD Newcrest estimate of adjusted book value.(1)1.4x transaction multiple estimated by TD Newcrest Analyst Doug Young and calculated as a percent of premiums, not book valu
12、e.United StatesCanada9 20% Premium, 16.0 x Price/Earnings, 1.6x Price/Book 50% Equity Consideration (132.5 shares delivered to existing shareholders of Sell Co.) $37 million after-tax cost of debt $30 million after-tax synergiesSimplified Acquisition Model - ExampleSource: Company reports and Bloomb
13、erg IBES estimates.Deal AssumptionsBuy Co.Sell Co.Share Price$10.00$20.00Shares Outstanding300100Market Capitalization$3,000$2,000Premium Paid20%Acquisition Price$2,400Acquisition Price per Share$24.002008 Earnings$300$150P/E (2008)10.0 x13.3xAcquisition P/E16.0 xBook Value$2,000$1,500P/Book1.5x1.3x
14、Acquisition P/BV1.6xSources and UsesSourcesCash$1757%Debt$1,15043%Equity$1,32550%Total Sources$2,650100%UsesPurchase of Equity$2,40091%Debt Refinanced$2008%Transaction Fees$502%Total Sources$2,650100%Other AssumptionsBuy Co. New Shares Issued132.5Cost of Debt5%Interest Cost of New Debt-$58After Tax
15、Cost of Debt-$37Synergies (after-tax)$30Total Adjust. to Net Income-$710 $1,150 of additional debt; 34% debt/capital ratio $1,325 new equity issued; equity of Sell Co. eliminated 2% EPS accretive after new shares issued, cost of debt and synergiesSimplified Acquisition Model Example Source: Company
16、reports and Bloomberg IBES estimates.Capital StructureBuy Co.Sell Co.AdjustPro FormaCash$75$100-$175$0Total Assets$5,400$3,700$0$9,100Debt$400$200$1,150$1,750Other Liabilities$3,000$2,000$0$5,000Equity$2,000$1,500-$175$3,325Total Assets & Liab.$5,400$3,700$10,075Debt/Capital17%12%34%EPS Accretio
17、n (2008)Buy Co.Sell Co.AdjustPro FormaEarnings$300$150-$7$443Shares Outstanding300132.5432.5Earnings per Share (EPS)$1.00$1.02Accretion/(Dilution)2%11 Sensitivity analysis highlights the impact on accretion of key deal assumptions Additional equity reduces accretion as additional shares are issued C
18、ost of equity is greater than the cost of debt Sell Co. acquired at a P/E ratio greater than Buy Co.Simplified Acquisition Model - ExampleSource: Company reports and Bloomberg IBES estimates.Sensitivity Analysis (2008 Earnings Accretion)2%0%10%20%30%$02%-2%-5%-7%$155%2%-1%-4%$309%6%2%-1%$4513%9%6%3%
19、2%0% 20%30%70%1%-2%-5%-8%60%5%2%-2%-5%50%9%6%2%-1%40%13%10%7%4%Purchase Price PremiumPurchase Price PremiumSynergiesEquity Consideration12 Excess capital of Buyer and Seller can be used to fund transaction The optimally capitalized portion of the Sell Co. business is valued at a full acquisition mul
20、tiple Excess Capital may not be valued at a full price/book multipleSimplified Acquisition Model - ExampleSource: Company reports and Bloomberg IBES estimates.Pro Forma Regulatory CapitalBuy Co.Sell Co.AdjustPro FormaRequired Capital$1,100$800$0$1,900Available Capital$2,000$1,500-$175$3,325Capital R
21、atio182%188%175%Minimum Target Ratio175%175%175%Excess Capital$75$100$0Adjusted Book Value of Sell Co.Book ValueBook Value MultipleEquity ValueCapital at 175%$1,4001.60 x$2,240Excess Capital$1001.00 x$100Total$1,5001.56x$2,340Base Case$1,5001.60 x$2,40013 Actuaries are an integral part of a P&C valuation process by providing forecasts for loss ratios, payout patterns, reserve development, and premium growth The valuation of a P&C company is often an iterative process where th
温馨提示
- 1. 本站所有资源如无特殊说明,都需要本地电脑安装OFFICE2007和PDF阅读器。图纸软件为CAD,CAXA,PROE,UG,SolidWorks等.压缩文件请下载最新的WinRAR软件解压。
- 2. 本站的文档不包含任何第三方提供的附件图纸等,如果需要附件,请联系上传者。文件的所有权益归上传用户所有。
- 3. 本站RAR压缩包中若带图纸,网页内容里面会有图纸预览,若没有图纸预览就没有图纸。
- 4. 未经权益所有人同意不得将文件中的内容挪作商业或盈利用途。
- 5. 人人文库网仅提供信息存储空间,仅对用户上传内容的表现方式做保护处理,对用户上传分享的文档内容本身不做任何修改或编辑,并不能对任何下载内容负责。
- 6. 下载文件中如有侵权或不适当内容,请与我们联系,我们立即纠正。
- 7. 本站不保证下载资源的准确性、安全性和完整性, 同时也不承担用户因使用这些下载资源对自己和他人造成任何形式的伤害或损失。
最新文档
- 初恋心理测试题(含详细答案解析)
- 初中物理新课标解读新
- 《高三物理上学惯性》课件
- 2026年《管理体系认证基础》真题试卷及答案
- 广东省中招数学科命题趋势分析
- 《高二数学反射变换》课件
- 工程光学第四章平面成像系统
- 《质量管理前沿领域》课件
- 关节置换围手术期抗血栓治疗
- 国外博弈论课件lecture
- 医疗机构疾控监督员培训考核试题及答案
- 2026秋川教版(新教材)小学信息技术四年级上册(全册)教学设计(附目录p124)
- 2026新修订离婚协议书范文
- 2026-2030中国羧甲基纤维素市场供需调查及竞争格局研究报告
- 7.1 集体生活成就我课件(共27张)+内嵌视频
- 铁路集团综合管理岗社会招聘笔试参考题库 含答案
- 2026年高考化学真题陕晋青宁卷含答案
- 2026年河北工人技师考评(环境噪声监测工)自测试题及答案
- 宠物毛发护理技巧
- DB32-T 5388-2026 电动车充电基础设施建设技术规程 第2部分:电动汽车
- 2026年人工智能赋能机械设计的新路径
评论
0/150
提交评论